What "Benefit Triggers" Mean and How They Affect Your Coverage
Your long-term care insurance policy doesn't pay benefits automatically when you need care. It pays when you meet specific conditions written into the policy — known as benefit triggers. Understanding exactly what those triggers are, and how your insurer evaluates them, is one of the most important things a policyholder or caregiver can know.
The Two Primary Benefit Triggers
Most modern LTC policies — particularly those issued after 1997 under HIPAA guidelines — use one or both of the following triggers:
1. Functional Impairment (ADL-Based)The policyholder must need substantial assistance with at least two of six Activities of Daily Living (ADLs):
- Bathing
- Dressing
- Eating
- Toileting
- Transferring (moving from bed to chair, etc.)
- Continence
"Substantial assistance" typically means either hands-on physical help or standby assistance due to a safety concern. The distinction between hands-on and standby matters — some insurers apply it narrowly to limit eligibility.
2. Cognitive ImpairmentThe policyholder has a severe cognitive impairment — such as Alzheimer's disease or another form of dementia — that requires substantial supervision to protect their health or safety. This trigger does not require ADL limitations to be present.
How Insurers Evaluate Benefit Triggers
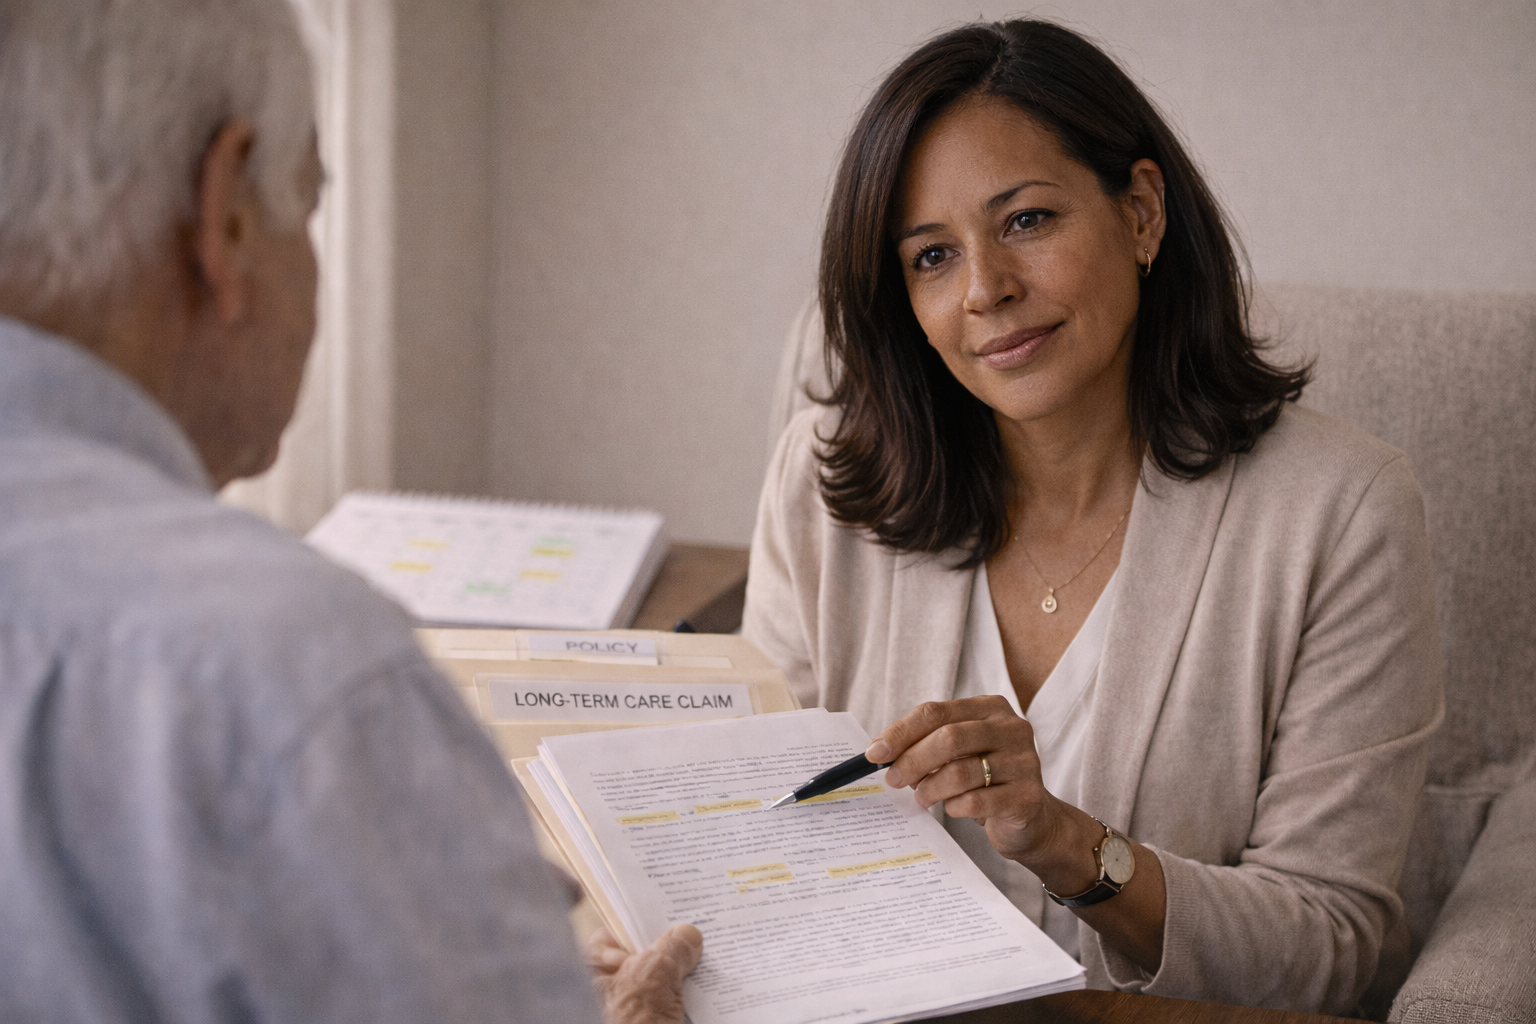
When you file a claim, the insurer will typically send a nurse assessor to conduct an in-person evaluation of the policyholder. This assessment determines whether the benefit triggers are met. The assessor's report carries significant weight in the approval or denial decision.
It is important to note that the assessor works for — and is paid by — the insurer. Their evaluation is not always neutral. If the assessment contradicts your physician's findings, you have the right to challenge it with independent medical documentation.
Older Policies May Have Different Triggers
Policies issued before the mid-1990s sometimes used different, more restrictive triggers — such as requiring prior hospitalization before benefits could begin, or limiting coverage to skilled nursing facility care only. If you are managing an older policy, review the benefit trigger language carefully — it may be substantially different from modern standards.
What This Means When You File
Before submitting a claim, document the policyholder's ADL limitations in detail. Your physician's statement should specifically address each ADL and describe the level of assistance required. Vague language like "patient needs help with daily activities" is not sufficient — the statement should name each qualifying ADL and describe the functional limitation explicitly.
Pro Tip
Ask your insurer in writing to define what they consider "substantial assistance" under your specific policy. Getting their definition on record before the assessment protects you if they later apply a more restrictive interpretation during the review.